Home

Bristol Myers Squibb’s complex net investment hedging solution

Published: Sep 2026
Adam Smith Awards 2026

Best Foreign Exchange Solution

Highly Commended Winner

Bristol Myers Squibb

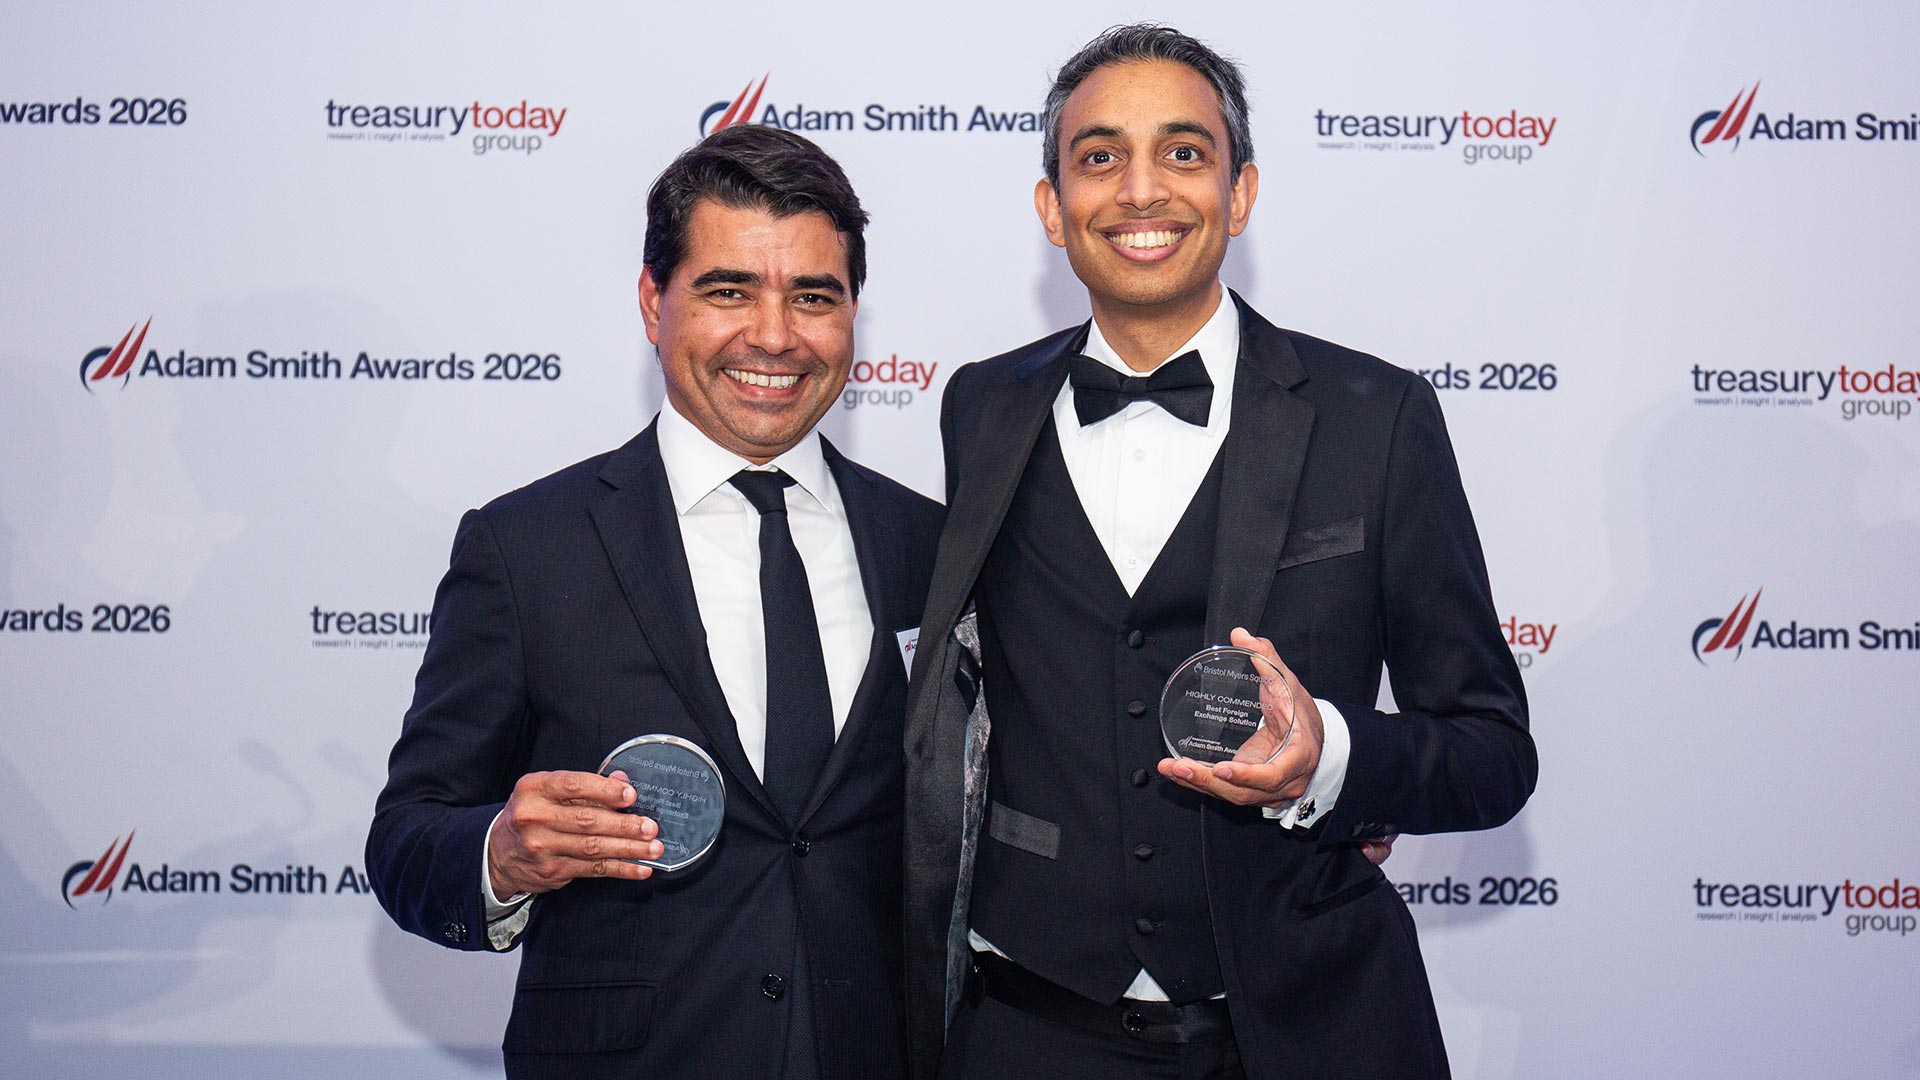
Photo of Hector Lugo, Bank of America and Ravi Patel, Bristol Myers Squibb.

Ravi Patel

Senior Director Financial Risk Management
Bristol Myers Squibb logo
United States

Bristol Myers Squibb is a global biopharmaceutical company dedicated to discovering, developing and delivering innovative medicines that help patients overcome serious diseases.

in partnership with

Bank of America logo

The challenge

For companies, dynamics such as restructurings and changes in business operations can lead to material volatility in foreign currency assets. It can also impact the permitted capacity for net investment hedging – a type of hedging that allows companies to mitigate the exposure of net assets denominated in foreign currencies.

When Bristol Myers Squibb (BMS) issued Eurobonds in 2015, these were designated as a net investment hedge of the company’s euro net asset position. But over time, the company’s net investment hedge liabilities began to exceed the net assets. The partial de-designation of the Eurobonds meant the bonds were now an FX balance sheet exposure which had to be hedged via negative carry FX forwards. Despite the partial de-designation, the risk continued as net assets remained in flux.

To address these challenges, BMS decided to de-designate its entire Eurobond portfolio – an exercise that included synthetically converting Eurobonds into USD and replacing the net investment hedge with shorter tenor EUR cross-currency swaps. The company later expanded its net investment hedging program to include new currencies.

Then, in response to changing market conditions, BMS began to assess alternatives to find a solution that was cost-effective, cash flow conscious, and flexible enough to adapt to the changing pharmaceutical landscape.

The solution

In partnership with Bank of America, Bristol Myers Squibb evaluated several hedging alternatives. These included not hedging, using FX forwards and cross-currency swaps across multiple tenors, and tandem hedging with CHF and EUR.

The approach ultimately chosen by BMS was also the most complex: a collar-based option strategy which would hedge foreign assets for modest moves in the currency, while leaving the exposure unhedged for larger movements. As such, this approach caps the potential cash inflow or outflows to predetermined amounts.

As an emerging approach to hedging net investments, this model is not widely adopted by corporates. However, its customisable nature meant that BMS could design a structure to optimise returns, while mitigating unfavourable cash outflows if USD were to weaken.

Best practice and innovation

BMS partnered closely with management, accounting and external auditors to gain approval for the strategy, while ensuring compliance and proper documentation. The team then developed the instrument type in its treasury management system to support the tracking and settlement of the hedges.

Preparing to execute the strategy, BMS set most of its FX forwards to mature at the end of Q125. Following internal alignment at the start of Q225, BMS then executed the inaugural capped collar transaction with Bank of America while EUR/USD was around 1.13.

Following the positive outcome, which reduced interest expense and limited cash outflow during periods of USD weakness, the company expanded the strategy to add other currencies.

The outcome

In aggregate for 2025, the newly implemented strategy outperformed all the alternatives that had been under consideration.

As a result of the project, BMS was able to meet the objectives of the net investment hedging solution, minimising unfavourable cash flows amid USD volatility and optimising the P&L benefit.

As Ravi Patel, Senior Director Financial Risk Management, observes: “In treasury, we aim to deliver value through strategies that can assist with delivering company objectives. This helps enable the company’s investment in innovation, ultimately bringing lifesaving medicine to patients.”

What the judges said:

“We’re excited and thrilled for this recognition so early in our journey as a standalone company. We look at this as a start, demonstrating the passion and expertise put in by our team to building a world-class treasury organisation.”

Bank of America congratulates Bristol Myers Squibb on their win for Best Foreign Exchange Solution. By partnering together to design an options-based net investment hedging strategy that meets the company’s goals and takes advantage of current interest rate differentials, Bristol Myers Squibb has successfully implemented an innovative solution that can be replicated by other corporates with similar net investment hedge programme goals. Bank of America is proud to partner with Bristol Myers Squibb as it leads the way in forward-thinking derivatives-based treasury solutions.

in partnership with

Bank of America logo
Adam Smith Awards sail

The Adam Smith Awards are the industry benchmark for best practice and innovation in corporate treasury. The 2026 awards attracted 635 nominations. To find out more please visit treasurytoday.com/adam-smith-awards

Join our global community

Creating a free account helps us to understand our community better, and tailor our content and events to suit your needs. You can unsubscribe at any time.
Already have an account? Sign in
Search for your company; if not found, select 'Other' and enter it manually below
  • • At least 8 characters
  • • At least 1 uppercase letter (A-Z)
  • • At least 1 lowercase letter (a-z)
  • • At least 1 digit (0-9)